Welcome to the high-stakes poker game of financial decisions. Every day, people face a critical choice: play it safe or go for the big score. It’s the fundamental tension between protecting what you have and chasing the maximum payoff.
This is the eternal dance between hedging and price improvement. It’s the age-old financial dilemma. Do you lock in a small, certain gain, or risk it all for a chance at the jackpot? It’s the financial equivalent of deciding whether to take the sure three points or go for the Hail Mary on fourth and goal.
This tension plays out everywhere. In the high-stakes world of illicit betting, a bookmaker might use a layoff to manage risk. This is their version of a hedge. To understand the mechanics, it helps to know what a layoff is in sports. It’s a tool to balance the books and minimize losses on a heavily wagered event.
On the other hand, in the corporate world, this principle is often disguised as a layoff. A company might cut costs by reducing staff to protect its bottom line—a form of corporate hedging against a downturn. Both the bookie and the CEO are playing the same game, just with different chips. One uses a layoff bet; the other, a pink slip.
So, is the goal to survive the night, or to own the casino by morning? Let’s explore how this gamble unfolds, from the backrooms of betting to the boardrooms of corporate America.
Triggers for Layoff (Liability, News, Liquidity)
Liability, news, and liquidity are the big three that can make a bookmaker or CEO jump into action. When the risk and reward are too close, these factors become urgent. They are the risks you don’t want to face, but they’re always there.
Think of your risk portfolio as a Jenga tower. Each decision is a block. Liability, news, and liquidity are the blocks that can make the tower fall. A sharp bookmaker or CEO knows which block to pull to avoid disaster.
The Liability Trigger: When Your Own Success Becomes the Enemy
Imagine a sportsbook on the eve of a big game. The public has bet big on the underdog, making the book heavy on one side. This is liability at its worst. The bookie sees a financial disaster coming, not just a loss. It’s about balancing risk, not winning every bet.
The News Trigger: When the World Changes at 3 AM
Now, picture the star quarterback getting hurt in practice. The news spreads fast, not just on the ticker. This is the news trigger. It’s a shockwave that changes everything. The market hasn’t opened, but the value of every position has already changed.
The Liquidity Trigger: When the Music Stops
The liquidity trigger is about not having enough money. It’s not about losing money, but not having it to cover losses. This is a structural trigger. It’s about survival, not probability. The only move is to lay off risk to keep going.
| Trigger | Bookmaker’s Nightmare | Corporate Equivalent | Immediate Action Required |
|---|---|---|---|
| Liability | Too much money on one side of a game; payout exposure threatens bankroll. | Overexposure to a single client, market, or product line. | Lay off (hedge) the unbalanced risk to another book or market. |
| News | Injury to a star player announced on Twitter 2 hours before kickoff. | Quarterly earnings miss, regulatory investigation announced. | Instantly adjust all related positions; lay off risk at new, worse prices. |
| Liquidity | Not enough cash to cover possible losses on Sunday’s big game. | Cash flow crisis; can’t meet short-term liabilities. | Aggressively sell/hedge positions to raise cash, often at a loss. |
Understanding these triggers is key for anyone managing risk. It’s not about avoiding risk, but knowing which risks to take and when to lay them off. This is the core of managing risk, whether in a sportsbook or a corporation. The goal is to manage risks before they manage you.
In the end, these triggers are about recognizing when a calculated risk becomes a danger. The smart player acts fast, not waiting for trouble. Next, we’ll explore where risk goes when it’s laid off.
Routing: Exchanges, Market Makers, Partner Books
Imagine a bet being placed and instantly moving through a digital maze. This isn’t just any bet; it’s a fast-paced race where risks are quickly passed on. Welcome to the heart of betting, where routing keeps everything balanced.
Think of it like air traffic control for finance. A bookmaker doesn’t just take on all the risk. They act as a router, spreading out the risk. They avoid being stuck with a big loss if an unexpected winner happens.
Then, there are the market makers. They are like the liquidity experts, helping bookmakers. They offer prices for buying or selling risk, like stock exchange specialists. They don’t just take bets; they make a market. This market making connects those who want to lay off risk with those who want to take it on, all while making a small profit.
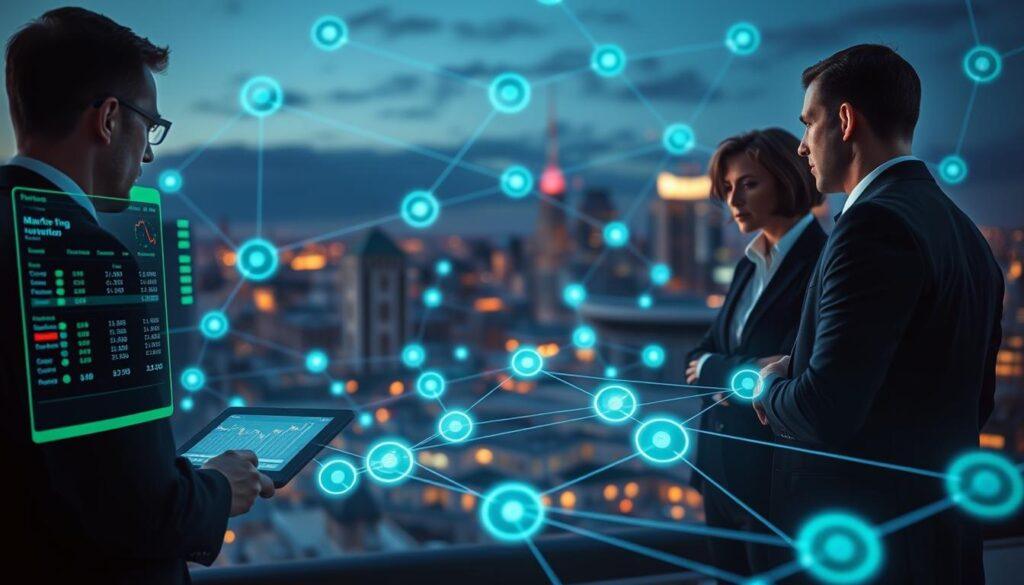
The routing doesn’t end there. The first place risk goes is often a partner book. This is a network of books that can take some of the action. Imagine betting on a big game. Your local bookie might take your $100, but they don’t keep all the risk. They might send some of it to a partner book in another place, which might send some to another network. It’s a complex, global system of sharing risk.
Why is this important? This system keeps the odds moving and the market liquid. Without it, sports betting would come to a halt. Next time you bet, remember it’s not just a bet. It’s a journey through a global network of risk-takers and market makers, all working to keep the odds and action alive.
Sizing the Hedge and Slippage Costs
Trying to size a hedge without a plan is like trying to build a complex strategy without instructions. You might have all the parts, but the result is unstable. Finding the right hedge size is about finding the least-worst option in uncertainty.
Your hedge acts as a safety net. If it’s too small, you’re exposed to market risks. If it’s too large, it can eat into your profits. The goal is to find the perfect size for your risk and the position you’re protecting.
The art of sizing a hedge starts with the layoff. When someone has too much exposure, they hedge to balance it. Calculating the right hedge size is tricky. Hedge too little, and you’re exposed. Hedge too much, and you lose on the hedge itself.
Slippage is a hidden risk. It’s the difference between expected and actual hedge price. In fast markets, this can be significant. You might plan to sell shares at $50, but get $49.75. This $0.25 is slippage, a silent tax on your risk management.
The real cost of hedging includes slippage, bid-ask spread, and market impact. For small trades, slippage is minor. But for large orders, it can be the difference between success and failure.
This creates a cycle. You hedge to protect yourself, but hedging itself can move the market. The more you hedge, the more it costs. Be strategic with your orders and timing to avoid high costs.
Sizing your hedge and managing slippage is a gamble. It’s about weighing known costs against the risk of doing nothing. You’re not just buying insurance; you’re pricing it in real-time. The goal is to manage risk, not eliminate it.
Hedge Accounting and Audit Trails
Forget the old ways of bookkeeping. In today’s finance world, the real challenge is making offsetting risk look legal. Hedge accounting and audit trails are key. They’re not just about keeping records; they’re about making your finances look perfect to regulators.
Hedge accounting is about matching the accounting of a hedge with the item it protects. It’s like keeping receipts for your financial moves. Without it, your offsetting risk plan is just a story.
The Bean Counter’s Dilemma: Gambler or Genius?
Corporate accountants and bookies face the same problem. They must prove their risky bets were smart hedges, not reckless gambles. The answer is a detailed audit trail. This isn’t about hiding anything; it’s about documenting every risk management move.
A proper corporate audit trail turns a speculative bet into a solid financial plan.
Why the Paper Trail is Your Get-Out-of-Jail-Free Card
An audit trail is more than just covering your tracks. It’s the story of your risk management. It explains every trade and hedge. When regulators come, you want to show them a detailed plan, not a napkin.
Think of it like a magician’s secrets. An auditor wants to see the tricks behind every financial move. Your audit trail proves your risk management is real, not just an illusion.
Anatomy of a Bulletproof Audit Trail
A good audit trail for offsetting risk isn’t just one document. It’s a detailed dossier that includes:
- Intent Documentation: The initial memo outlining the risk, the proposed hedge, and the expected correlation.
- Execution Records: Timestamped trade confirmations, counterparty confirmations, and market data at the exact moment of the hedge.
- Effectiveness Testing Logs: Ongoing proof that the hedge is actually doing its job of offsetting risk. This is where you prove the magic trick works, every night, twice on Sundays.
- Periodic Assessments: Quarterly and annual reports that re-assess and document the hedge’s effectiveness, showing regulators and investors you’re not just winging it.
The Showdown: Hedge Accounting Methods
Not all hedges are the same, and neither are the accounting methods. Your choice is about the story you want to tell on your balance sheet.
| Method | How It Works | Best For | The Paper Trail Focus |
|---|---|---|---|
| Fair Value Hedge | Hedges the change in the fair value of an asset/liability. Think of it as insuring the value of an asset you already own. | Firms with large, specific asset/liability portfolios. | Intense. Requires proving the exact risk being hedged and the hedge’s effectiveness in neutralizing it. |
| Cash Flow Hedge | Hedges the risk of variable cash flows from a forecasted transaction (e.g., a future purchase). | Companies with predictable, forecasted transactions, like buying commodities or foreign currency. | Heavy on documentation of the forecasted transaction and the hedge’s effectiveness in locking in a rate. |
| Net Investment Hedge | Hedges the currency risk of a net investment in a foreign operation (e.g., a US parent company’s investment in its European subsidiary). | Multinational corporations with significant foreign operations. | Focuses on exchange rate movements and the net investment’s value. The audit trail must link the hedge directly to the foreign investment. |
Choosing the right method is strategic. It tells your stakeholders if you’re playing defense or offense with your offsetting risk strategy.
The Final Ledger
In the end, hedge accounting and its audit trail are your alibi. They turn a speculative bet into a managed, documented, and defensible business strategy. It’s the difference between looking like a riverboat gambler and a grandmaster chess player.
As highlighted in discussions on modern risk management, the sophistication of your models is irrelevant if you can’t prove the logic behind the hedge. The paper trail isn’t just bureaucracy; it’s the evidence that your offsetting risk strategy was a calculated business decision, not a roll of the dice. In the high-stakes game of finance, the best hedge is a good paper trail.
Case Studies: Derby Day, Bowl Games
Forget the Super Bowl. For a bookmaker, the real stress tests are the Kentucky Derby and the College Football Bowl season. These events are more than just games; they’re the ultimate test in market making. Here, hedging, routing, and managing liability are put to the test.
The Kentucky Derby is a perfect storm. The whole world bets, and they all bet on the favorite. This creates a huge risk for the bookie. It’s not just about betting on a horse; it’s a high-wire act of risk management.
Switch to the chaos of Bowl Season. The action is fast, the betting sharp. This is where the “wise guys” play. The market making gets sophisticated. The bookie’s lines are constantly tested by professional bettors.
These events show market making isn’t about picking winners. It’s about managing a book. The bookie isn’t betting on a horse or a team. They’re managing a portfolio of risk. The Derby and the Bowl Games are the final exam, proving that successful market making is about staying in the game when the whole world is watching, and betting.